
Life's work, carried forward
Why Freyr exists, and why planning for Inheritance Tax earlier matters now.
Nick Maidment

At school, my children are taught a little rhyme: you get what you get and you don't get upset. It's a lovely lesson for the playground. It's not such a good one for planning what happens to everything you've worked for.
For a long time, estate planning has felt a bit like that. Clients took what was on offer, and advisers made the best of it. I wanted to build something different: a service shaped by what advisers and their clients actually told us they wanted.
So, we asked, we listened and we built Freyr around their answers.
What two decades in the market taught me
I've spent more than twenty years in financial services, across the UK and Australia. Eleven of them were in multi-asset sales at Deutsche Bank and UBS. The last ten were in estate planning, where I led sales and customer at Octopus Investments, was responsible for around £1bn of inflows a year and helped launch its business in Australia.
That meant sitting across the table from hundreds of advisers and hearing what their clients actually wanted. Most of the families I've met want the same three things: to see what they've spent a lifetime building passed on to those most important to them, for it to keep growing in the meantime, and to keep access to it in case later life costs more than they'd planned. After all, nobody wants their money sitting still for the rest of their lives and hardly anyone spends decades building something in the hope that HMRC ends up with a large share of it.
Advisers and planners told me what they needed too: something they could explain to clients simply, charges they could justify, and a partner who picks up the phone and is still there long after the first investment.
I've never liked compromise. It's settling for less. So, planning for Inheritance Tax and growing wealth at the same time shouldn't mean choosing one over the other. I think families deserve both, and advisers should be able to offer both with confidence.
That's the idea Freyr is built around: a life's work, carried forward.
What Freyr does
Freyr is an FCA-regulated investment manager, set up in 2024 to work alongside financial advisers. Our Estate Planning Service is designed to help clients plan for Inheritance Tax and it uses Business Relief, a long-standing relief that may apply to qualifying investments after two years. The return is designed to come from private credit: lending to UK businesses, via specialist lenders, with security behind every loan. It’s an area of the market that has grown by around 13% a year since 2013 after banks pulled back from lending to smaller UK companies following the financial crash.
I joined in 2026. I loved my time at a large firm and learnt a great deal there, and it gave me the experience and the relationships to do this. But I wanted to start from a blank page and ask a simple question: if you designed estate planning around the client and their adviser from day one, what would it look like?
Freyr is our answer to that.
Plan in your sixties, not your eighties; why this matters now
Because Business Relief can apply after just two years, it often gets left late and treated as a race against the clock. Two years is a useful safety net if you need one but it's a poor place to start from.
Estate planning belongs in your sixties, while you're healthy, in control and still have choices, and it shouldn't be done alone. The family should be in the room, because the hardest part of inheritance isn't the tax, it's the first conversation.
Something also changes on the 6th of April 2027. For the first time, most unused pensions fall inside the estate for Inheritance Tax. What you draw and when has become an estate planning decision too, and plenty of people in their sixties are about to become estate planners without realising it.
It isn't the only thing moving. The nil-rate band has sat at £325,000 since 2009 and is now frozen until April 2031, while people's property, pensions and portfolios have carried on growing. The Office for Budget Responsibility expects Inheritance Tax receipts to rise from £8.2 billion in 2024/25 to more than £14 billion by 2030/31, ² and something in the region of £5.5 trillion is estimated to pass between generations in the UK in the thirty years to 2047. ³
Behind every pound of that is a person and I'm determined to help more of what families have built reach the people it was built for.
Where the money goes
I also wanted the money to be doing something I'd be proud to explain. So we lend in four areas we know well: Ofsted regulated homes for children who need somewhere to live, IT support for smaller businesses, the handover of advice firms as their founders retire, and new homes built by experienced developers. These are businesses people depend on, and the return is designed to come from the loans being repaid with interest.
We target a 6.5% net annual return, and I think more of what the money earns should end up with the person who invested it. That’s why there is also no annual management charge for simply holding the investment. My children are told that sharing is caring, and that's one playground rule we've happily kept: we only get paid a performance fee (0.5%) once clients have received that return. Nothing is guaranteed, and capital is at risk, but I'd rather set the bar where I'd want it if it were my own family's money.
The relief shouldn't be doing all the work
Business Relief is genuinely useful, just don’t make it the whole reason you invest. The rules move, and when they do, a tax-led decision can fall apart fast. They've already changed this year and they may change again. So, the question I ask myself is a simple one: if the relief disappeared tomorrow, would this still make sense as an investment?
We've built Freyr so the answer should be yes. Because the return is designed to come from lending to smaller UK businesses, where every loan is legally secured, and an independent trustee holds that security for investors, the relief is a bonus on top.
That bonus has been tested too. When one of the first investors in the underlying lending company died, HMRC reviewed their holding and confirmed it qualified, so no Inheritance Tax was due. A single case says nothing certain about anyone else's, but it is the kind of evidence I would want to see myself.
A life's work, carried forward
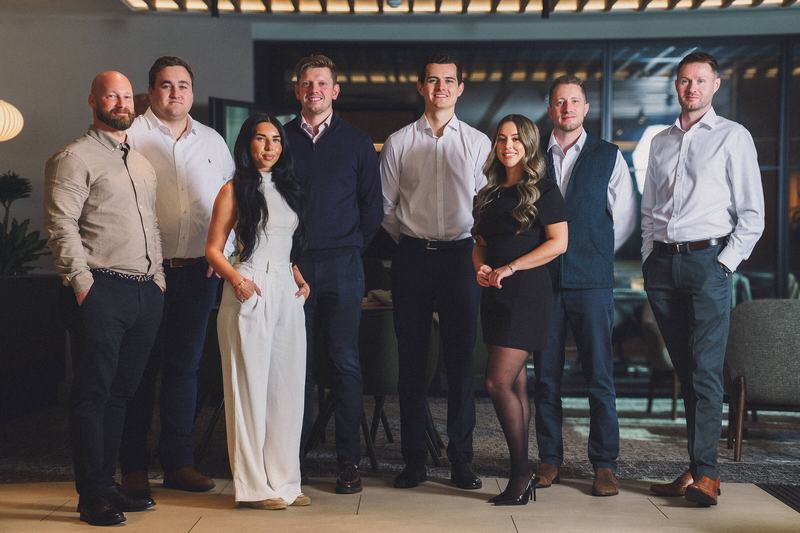
I've spent this year building a team around people with real experience in financial services. At our first get-together, we wrote down everything that frustrated us about the industry we've all worked in for a long time, and then everything we love about the businesses we've dealt with as customers, whatever industry they're in. We put a whole lot of sticky notes side by side and turned them into our own standards, which aim to raise what advisers, planners and clients can expect.
Families deserve a plan that keeps what they've built growing and gets more of it to the people who matter most to them. Their advisers deserve a partner who helps them deliver it. That is the standard we've set ourselves at Freyr.
If you're an adviser, I'd like to earn your trust by answering your questions properly and doing what we say. If you're a family, I hope this reads like the conversation you wish someone had started sooner. Either way, ask us anything, and if we get something wrong, tell us. We were all taught that honesty is the best policy, and it works both ways.
Capital is at risk and investors may not get back the full amount invested. Target returns are not guaranteed. Business Relief qualification is assessed by HMRC case by case and is not guaranteed, and tax rules can change. Investments in unquoted companies are illiquid and are not covered by the Financial Services Compensation Scheme. The case referred to relates to one investor and is not indicative of the outcome for any other investor.
¹ UK Finance, UK Public and Private Markets, March 2025. Outstanding private credit at end 2024.
² Office for Budget Responsibility, Economic and fiscal outlook, March 2026. Figures are a forecast.
³ Cebr for Kings Court Trust, "Passing on the pounds", February 2017. Estimate of inheritances and lifetime gifts, 2017 to 2047.
Freyr Investment Management Ltd is authorised and regulated by the Financial Conduct Authority, Firm Reference Number 1016385. Registered in England and Wales, company number 15490639.

